Credit-card delinquencies are likely to become the next
flashpoint in the credit crisis, though the impact on the overall
economy won't be as severe as the housing slump, analysts believe.

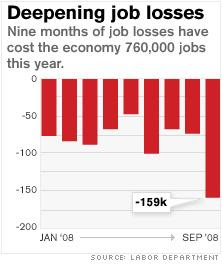
As the economy worsens and unemployment rises, more
Americans are having trouble paying off their credit card balances.
That has pushed up losses for credit card issuers, forcing them to
tighten standards, which puts a further squeeze on cash-strapped
consumers.
“After mortgages and home equity, credit cards are the
next in line to feel the crunch,” says Marc DeCastro, an industry
analyst with Financial Insights.
With job losses growing, credit cards delinquencies
could rise to 7 percent by the first quarter of 2009, which would
be a 20 year high, says Howard Shapiro, an industry analyst with
Fox-Pitt Kelton.
And because consumers no longer have the equity in the
house to fall back on, they're relying even more on credit cards to
pay for living expenses.
“Now with their home equities getting shut off, people
are going to start augmenting their income with their credit
cards," DeCastro says. "They are going hit their limits and once
they hit their limits, then they are probably going to walk away
from their credit cards.”
Though consumer spending accounts for three-quarters of
the US economy, the credit-card crunch isn't likely to be as big an
economic blow as the housing crisis has been.
The reason is that credit card debt, while still large,
is much smaller than the amount tied up in mortgages.
There is roughly $1 trillion of outstanding credit card
debt—compared to $14 trillion worth of outstanding mortgages—and in
the second quarter of 2008, $385 billion of this had been bundled
into asset-based securities, according to the Securities Industry
and Financial Markets Association
Another reason for the smaller fallout is that credit
card issuers have been working over the past year to tighten
standards and limit the damage.
“I don’t see the credit card industry facing the kind
of stress that the mortgage industry has faced," says Shapiro.
"They have had time to prepare, to tighten their underwriting
standards which were not stretched to the same degree as they were
in the mortgage industry."
Still, that doesn't mean the growing losses aren't
going to hurt.
Credit card write-offs last year totaled $26.6 billion,
and are on track to reach more than $41.4 billion this year. And
that's just the beginning.
“We think 2009 is going to be a difficult year for the
credit card industry," Shapiro says. "There’ll be higher charge
offs, slower growth, people are cutting back on spending. That is
going to mean pressure on earnings.”
Innovest Strategic Value Advisors forsees delinquencies
rising through the next three quarters, peaking at 10 percent, with
industry losses of close to $100 billion in 2009.
this is the beginning of the worse to come!