Australia:
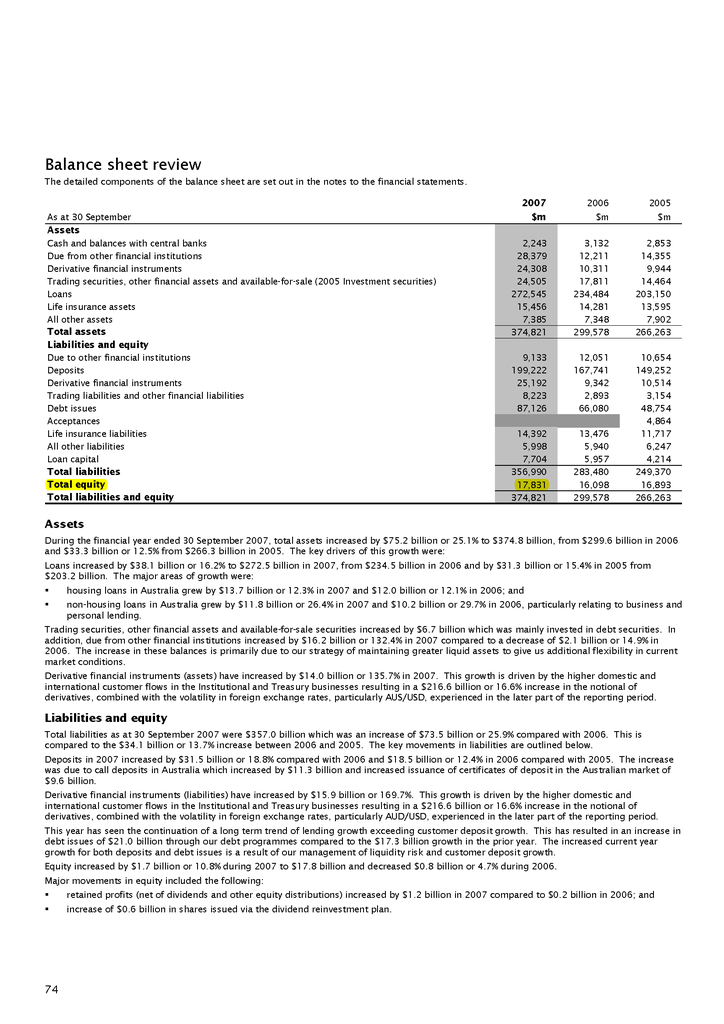
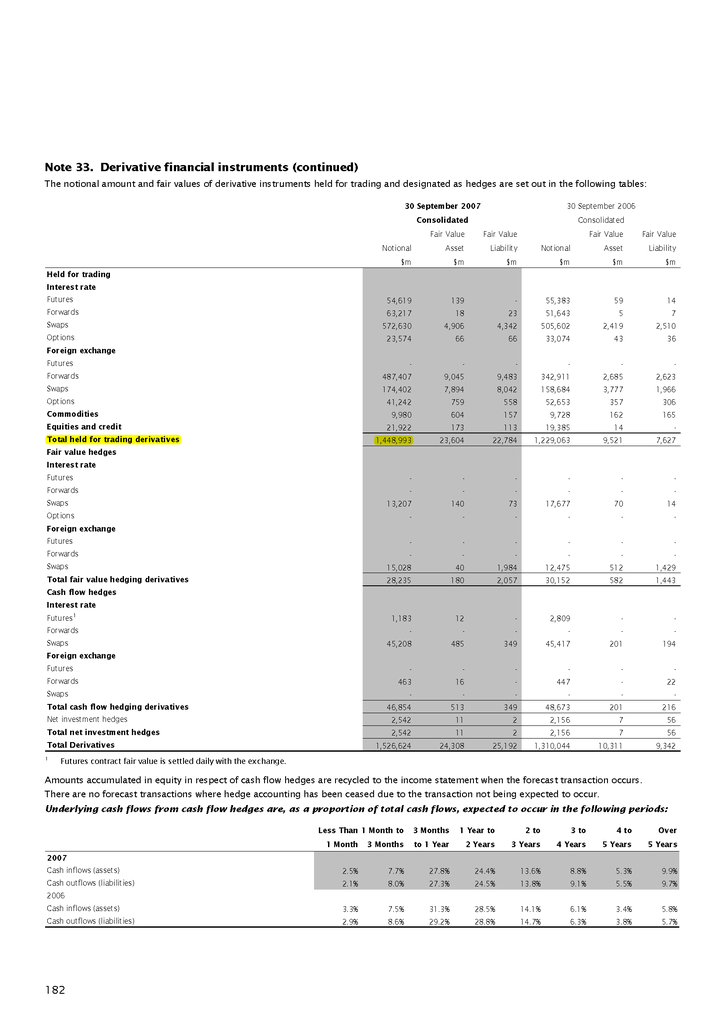
Interestingly I looked up the Westpac Bank (Australia),
true enough it had a derivatives position of AU$ 1.449 trillon and
an equity of only AU$ 18 billion.
Derivatives Gearing = 1,449 / 18 = 80.5 times
Singapore:
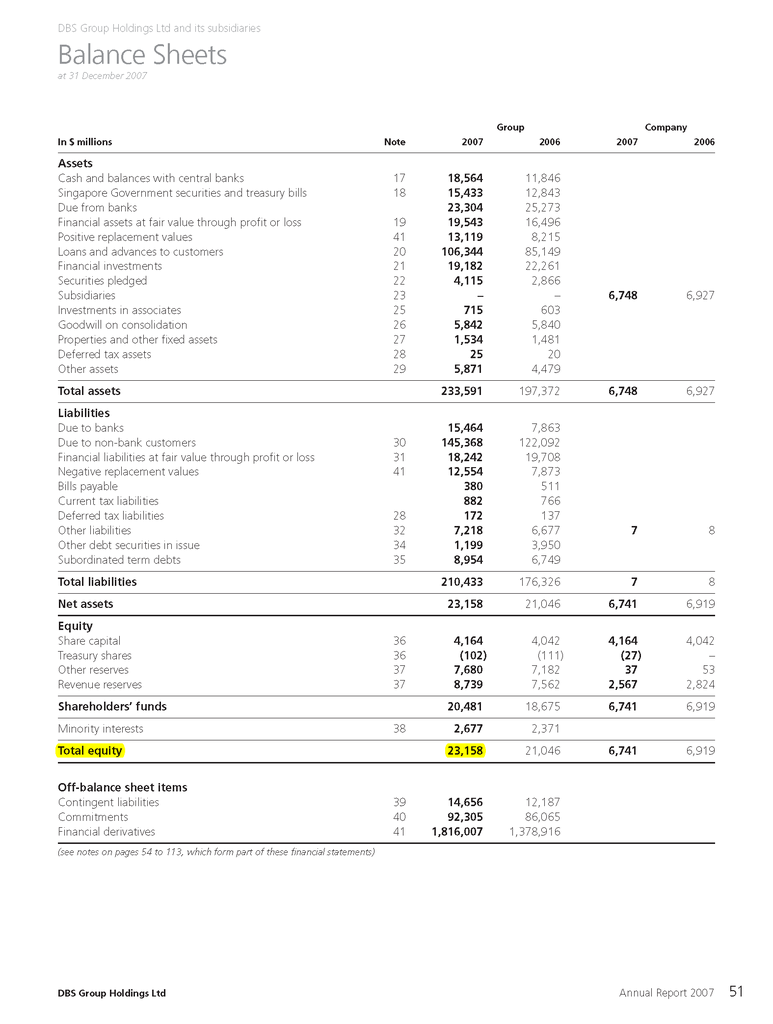
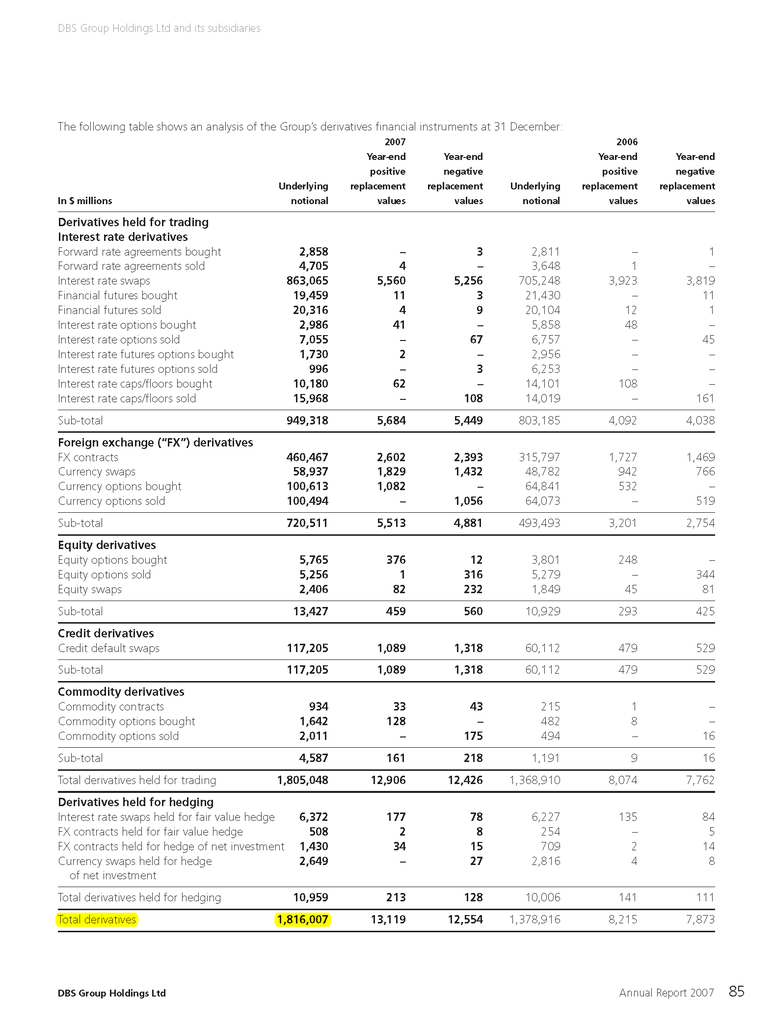
Then I had a look at DBS (Singapore) Balance Sheet, it had a
derivatives position of SG$ 1.805 trillion and only an equity of
SG$ 23 billion.
Derivatives Gearing = 1,805 / 23 = 78.5 times
So does this also mean that Singapore Banks are highly geared
for failure like the Australian Banks?
Westpac
Australia
DBS
Singapore
Source:
Westpac Financial Statements 2007
Source:
DBS Financial Statements 2007
omg! that's sound bad.
