Posted by theonlinecitizen on February
25, 2008
 By
Selene Cheng
6.5 million people. That
is the projected number of people our government believes
Singapore
can
accommodate. Already, 80% of the population lives in subsidised
housing, and with the development of estates in Sengkang and
Punggol, no one will have to be a vagrant. No one will have to
sleep under the void deck with aluminium cans for a pillow, or at
the beach with the sky as their blanket.
Unfortunately, nothing
could be further from the truth. Being homeless in
Singapore
is a real
possibility, as theonlinecitizen (TOC) has found out, and you don’t
even need to be old and dirt poor in order to have no roof over
your head.
In
this special feature on home ownership in Singapore,
theonlinecitizen tells the story of Andrew, a 34-year old young man
who will soon be out of a home in 3 months because of the Housing
and Development Board’s (HDB) lack of compassion and
flexibility.
In the
beginning
Andrew has a family of
four: his father, his mother, (both in their sixties), himself and
his sister. His father is a real estate agent. In 1992, the family
bought an executive maisonette, taking out a mortgage loan of
$464,100.
The family woes started in
1991, when Andrew’s father, the sole breadwinner then, started
chalking up less sales. Despite the financial difficulties, his
father managed to pay the instalments.
It
was not to last for long. In 1996, the property slump severely
affected his father’s income. Andrew’s father went into debt, and
could not afford the monthly mortgage loan repayments, the
utilities and the service and conservancy charges (S &
CC).
14 instalment plans and
family conflict
Because the family could
not afford to pay for the utilities, they worked out instalment
plans with Singapore Power (SP). TOC understands that the family
has drawn up 14 instalment plans to date since 1999, and the family
have kept to the plans with varying degrees of success.
“My father was always a
dollar short and a day late,” said Andrew. “He tried driving a
taxi, being an agent at a maid agency, but the money was never
enough (to cover the bills). So he was always struggling to find a
job (that paid enough).”
“For a good 10 years (1996
– 2006), he was out of a (stable) job.”
Because of the family’s
inability to make repayments, the family’s electricity and water
supply was often cut off. Andrew estimates it has been about 20
times now. The stress of being unable to repay the mortgage loan
and the frequent utilities disconnections took a toll on the
family. “Our quarrels just seemed to escalate,” said Andrew. “We
always argued about why (we have) no money to pay, whose
responsibility it is to pay, why my father can’t get a job,
etc…”
“There was so much finger
pointing”, he said wistfully..
Utilities cut so many
times, he knows the routine
Andrew’s electricity and
water has been cut off so many times he knows the drill already.
According to Andrew, a Singapore Power (SP) representative comes,
rings the doorbell, the family opens the door and pleads with the
representative not to cut off their utilities. The discussion ends
with his father signing a document undertaking to pay the arrears
plus late payment penalties etc.
One family member then
goes down to the SP office with the signed document to “settle” the
matter, and a technician would be sent to reconnect the utilities
the same day. Andrew said that the SP office usually asked them to
pay in full, but because the family could not, they would “pay
something, like anything” and their utilities would be
reconnected.
“There were times my
entire family survived on my mother’s $600-$800 salary as a
part-time worker in Yoshinoya to pay the bills,” said
Andrew.
Lack of compassion from
SingPower
 The most recent incident
in January 2008, however, showed SP’s lack of
compassion.
The family owed SP $2000+
in utilities, and they had kept to their latest repayment plan of
$250 monthly. However, once they missed just 1 month’s payment last
year, an SP representative was sent to disconnect the supply in
January.
Andrew
recounts that that day, the technician had rang the doorbell, but
because his father was in the toilet, no one came to the door. The
SP rep thus proceeded to disconnect the supply.
Halfway while Andrew’s
father was doing his business, the light in the toilet went off.
Realising that the electricity had been cut off, Andrew’s father
rushed out of the toilet in a panic and pleaded with him, saying
that he’d sign whatever was needed, as long as the electricity was
reconnected. But Andrew said that this time there was no discussion
and no immediate reconnection.
“The man didn’t even want
my father to sign anything, he just repeated again and again, ‘I’m
sorry sir, I’m just doing my job’, and asked us to go down to the
SP office to settle with them,” said Andrew.
“What
kind of system has created an employee that fears the system so
much that he doesn’t even dare to go beyond what he was told he was
supposed to do?”, said Andrew. Upset, he called the SP Customer
Service Centre.
 “Where’s all the
compassion in all this? I’ve been through all this before, I know
the procedure,” said Andrew. He explained to the customer service
officer that the previous reps had always discussed the issue with
them, and had always reconnected their supply. In response, said
Andrew, the SP Customer Service Officer “proceeded to give (him) an
education on what is supposed to happen” and repeated the procedure
that Andrew already knew, reiterating that if nobody answered the
door, they have a right to disconnect the power
immediately.
“I
told them, ‘I know the procedure. But why the previous people who
came to disconnect can be compassionate, just sign the paper and
they’ll reconnect immediately? Why not this time?”, he
asks.
It
was evident that the talk with SP was fruitless, for Andrew said
that his father was soon served a letter demanding payment by 5 Feb
with no exceptions.
Andrew added that the
amount was originally in arrears for $2000+, but as of Jan it had
been paid down to $700+.
“That shows our effort
since we made our first arrangement with SP that we pay, every
month,” said Andrew. He said that they always paid the current
charges plus a bit more to offset the original debt. The $700+
would have just taken a few more months to pay off.
“But the hammer just comes
down on us, and I don’t understand why. I don’t understand
that.”
No mercy from HDB
either
 Andrew’s woes are not
confined to SP charges alone. Andrew will soon be homeless as well,
because the family cannot afford the S & CC and the mortgage
loan repayments, the latter of which have to be paid in cash (no
CPF because his father is self-employed).
Andrew explains that since
April 1999, they have received financial assistance in the form of
deferred payments for their S & CC, or smaller payments of the
interest only. Andrew makes it clear that they have only received
these concessions due to their constant pleading.
“I
estimate my father has gone down to HDB to plead about 10 times
already,” said Andrew. “We’ve also pleaded with them through our
MP, Mr Wong Kan Seng, at least for 5 years already.” Andrew said
that each time HDB sends them a letter demanding payment, his
father goes down to the HDB office to pay a little to keep the
family from being continually hounded.
Andrew’s father had had a
repayment plan of $120 per month for the S & CC charges, but
had not been able to pay still. The HDB’s “compassion” finally ran
out. In November last year, the family was served a lawyer’s letter
demanding they pay their 20 months’ worth of S & CC charges of
around $2000. The actual arrears amount to $1600+, while the
remaining is a penalty for late payment.
HDB also turned down their
appeal to make partial payments of their monthly house loan
instalments as they had been given extensions. The original
instalments were $2000+ per month, but are now $3000+ (including
penalties for late payments). A letter issuing an ultimatum was
sent to them, telling them to register their flat for sale by 28
Jan, and sell the house within three months.
When asked why they did
not sell the house earlier, Andrew replies that the property market
was not good, and if they sold the house, they would have made a
massive financial loss and still be in debt to HDB. “My dad’s
intention all the while is for the house value to appreciate, so he
can cover all debts, be free of this burden of being in debt to
HDB,” said Andrew.
He
also adds that his father recently had been sent a letter,
informing him (father) that he had been barred from applying for a
HDB season parking ticket because of the S & CC arrears. The
move has made the family worse off financially, said Andrew, as his
father needs the car (and therefore season parking ticket to park
the car) for his work as a real estate agent.
“Finding a house is tough
as hell in Singapore”
The family has no choice
but to sell the house. The sale means that Andrew’s father will
lose his entire lifetime of CPF savings. But Andrew sees a glimmer
of sunshine in the gloom. The property market is good now, and
their house has had a good valuation; the money they get from the
sale will cover all SP, S & CC, and mortgage loan money they
owe.
Andrew’s parents’
eligibility to apply for a new HDB loan is in doubt because of his
father’s debt history. Andrew himself, though, is going to get
married, and he and his fiancée have the ability to buy a new
house. The plan is to have their parents stay with them.
The problem, however, lies
in finding a house within the tight deadline of three months.
“Finding a house is tough as hell in Singapore,”
said Andrew. He said that if they bought a resale flat, they would
have to pay a cash top-up of at least $30,000 - $40,000, and on top
of that the 10% downpayment for the HDB loan. Andrew said that he
and his fiancée have the means to service the HDB loan, but not
enough to cough up a $30,000 cash top-up.
Andrew said he has been
looking for flats with a cash top-up of $5000-$10,000. Andrew and
his fiancée have viewed about 30 units so far since August 2007,
but have not managed to find one within their budget.
Immediately he corrects
himself – he did find one within their budget. “We saw one house in
Sengkang, ground floor unit, 4-room, asking for $5000 cash (top-up)
only,” said Andrew. “And we said, ok, we want, but when we called
up 2 hours later, after we had viewed the house, the agent said [it
had been] sold already. Because after I left, another 4 people (had
come), and one person offered $7000, the other offered $10,000, and
the last offered $20,000,” said Andrew. “It was like bidding, you
know,” said Andrew.
“So the loser is the one
who doesn’t have the cash lah.”
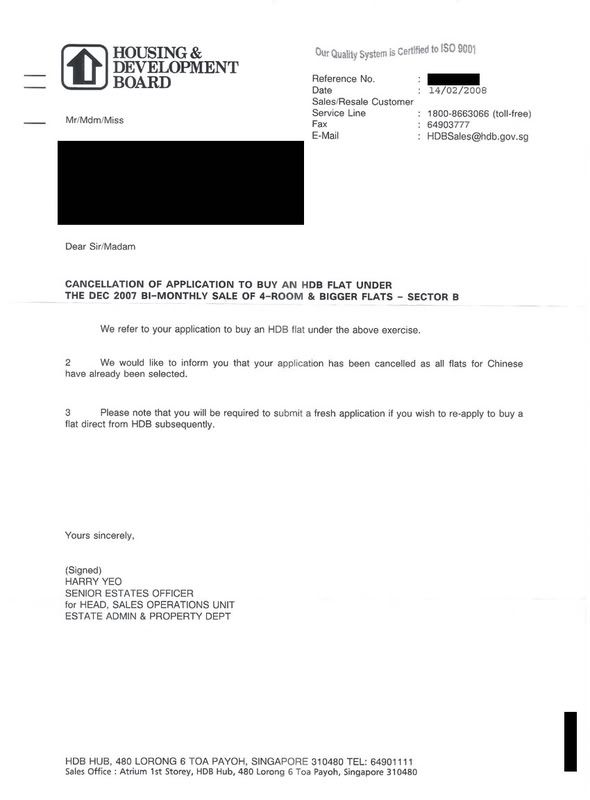 Andrew said that he also
tried balloting for a flat, but was unsuccessful. He had applied
for a flat in both mature and new estates, even unpopular estates,
and each time his queue number has been unfavourable. In the recent
Sengkang balloting exercise, he said that the 400+ units attracted
5,000 applicants, and his queue number was 2600. A recent balloting
exercise for 200 units in mature estates attracted 10,000
applicants, of which he was number 5938.
Andrew said he read on the
HDB website that those who had submitted more applications and
failed to get a flat would be moved up further the queue. “But
nobody knows how many people are in the queue,” said Andrew.
“Nobody knows how many have played this game, and (applied
repeatedly) just to get ahead in the queue, and each application is
$10 you know,” said Andrew.
“I
wonder, how many houses are out there in HDB ready to be sold, and
how many are actually being released in every batch?”
“Is this a money churning
exercise?”
No priority given by HDB
for family to buy flat
Andrew is desperate to
find a house, “any house”, he says, for if he cannot get a flat
within the next 3 months, he and his family will be homeless.
Andrew said that he even went down to the Bishan HDB office to find
out what he could do. The staff who served him told him that “even
as staff (they didn’t) have priority to know what are the units
that are not being released”.
“Is there such a system
that says that for those who truly need it on a case-by-case basis
we give you priority?”, he asked.
“Because I’m going to be
homeless!”
Homeless
in Singapore?
It
is highly likely that Andrew’s case is not an isolated one. For
more than 15 years, Andrew has slept through hot nights and used
candles for lighting. He is helpless to improve his situation much.
He does not have a degree – he is self-employed – his income varies
from month to month, and he explains that he would earn even less
than what he earns now if he took a regular job.
Andrew’s plight also
brings up more disturbing questions. Why do repeated appeals from
an esteemed MP to the HDB and SP have seemingly little effect? Why
must the HDB – a quasi-government body, no less – and SP, a major
utilities provider, be so hard on one down-and-out old man? What is
the breakdown of the number of people who have balloted more than
once in order to get a higher priority in the queue for flats? Is
balloting a money-making exercise after all, despite HDB’s claim
that balloting is to give everyone “a fair chance”?
In
summary, these are the problems that Andrew and his family
face:
1.
They must put their flat on the resale market by
Jan 28,
2008.
2.
Repay $464,100 of mortgage loans
3.
Pay the $700 in utilities
4.
Pay their Town Council $3000 in S&C charges
And even if they manage to
pay off the debts, Andrew and his family may still end up on the
street – because he can’t afford a resale flat and the queue for a
new flat will take some time.
Yet, despite all that he
is going through, he only asks that the HDB considers his
circumstances and maybe move him up in the queue for a new
flat.
Andrew says that this is
an opportunity for his family to finally get out of the cycle of
being in debt for so long – if only the HDB would be compassionate
about his situation.
There are questions that
only the relevant authorities can answer. The clock is ticking, and
for those like Andrew who are stuck between a rock and a hard
place, their next home may be the void deck. Let us hope that it
will not be for lack of compassion from our government that people
will sleep outside at night.
Otherwise, thanks to the
HDB, a family will be homeless.
NOTE:
Andrew’s friend, Leong Sze
Hian, who alerted TOC to the story, says:
How many Singaporeans are
there like my friend, Andrew and his family, who may lose their
home, and their life CPF savings, because they cannot pay for their
HDB flat?
With the apparent
“disappearance” of the flats given financial assistance statistics
in this year’s HDB Annual Report (this statistic was in past Annual
Reports - the previous year’s figure was 28,386), how many can’t
pay?
When the HDB makes a
demand for a flat owner to sell his or her flat in the open market
by a certain deadline, will it disappear from the “financial
assistance” statistics?
Will it also disappear
from the “flats repossessed by HDB” statistics? (360
flat-owners voluntarily surrendered their flats from 2003 to
2006 - reply to question in Parliament, March
2007).
Read also:
“HDB’s mistake but she’s made
to pay - 4 years later”.